
As member-owned, nonprofit institutions, credit unions balance financial performance with a broader responsibility to the people and communities they serve. On the one hand, this is a good thing, as that structure shapes how decisions are made, with the community in mind. On the other hand, that same structure makes it harder to compete with larger financial institutions for talent and resources.
Today, those pressures are increasing.
Credit unions are navigating a mix of regulatory expectations, cybersecurity risk, lending exposure and workforce challenges, often with lean internal teams. What was once manageable within traditional operating models has become more complex.
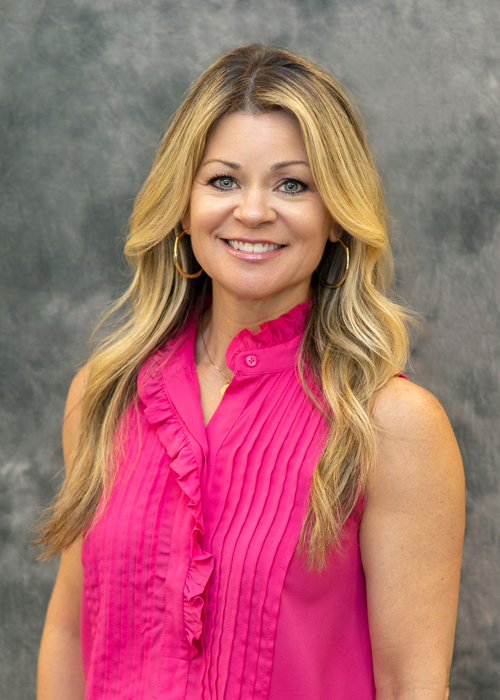
“The challenge isn’t just managing risk or supporting employees,” said Bridget Fazzolara, SVP, Employee Benefits, NFP. “It’s understanding how those things connect. For many of our clients, we help them make sense of how those pieces fit together based on how their organization is structured and what matters most to their employees and members.”
As lending portfolios continue to evolve – with exposure across auto, mortgage and commercial products – they require more active management. At the same time, enterprise risk is expanding, from cyber threats to governance and compliance expectations. Workforce strategy adds another layer, as credit unions work to attract talent, retain experienced employees and plan for leadership transition.
These are not separate issues.
Decisions made in one area often influence outcomes in another. For example, lending strategy affects capital; workforce decisions affect service delivery; risk management affects long-term stability. For many credit unions with leaner teams and limited specialized resources, recognizing those connections is essential to managing growing complexity.
However, most credit unions are not structured with in-house teams across all these areas at scale. And for many, building those capabilities internally is not practical. For those who need access to expertise beyond product placement or transactional support, the challenge is finding a partner who can manage complexity across lending, enterprise risk and workforce strategy in a coordinated way.
That need shows up in different ways.
Competing with larger financial institutions is one example. It requires an approach that balances cost with the need to retain experienced employees and plan for leadership transition. Without the scale of larger organizations, many credit unions explore more flexible strategies, from shared risk models in benefits to executive programs designed to support retention and long-term planning.
“Most credit unions don’t need another vendor,” said Fazzolara. “They just need someone who understands what makes credit unions unique, and build strong and sustainable solutions that overcome the cost challenges while maintaining exceptional benefits for an employee centric culture.
Credit unions are also looking for ways to expand the value they provide to their members, particularly as those members face many of the same pressures. Business members in particular are navigating rising costs, workforce challenges and increasing risk, and are looking to their credit unions for guidance that goes beyond traditional financial services. Institutions that have built relationships to extend their reach are in a strong position to support their members in new ways, while the credit union remains at the center of the relationship.
Expectations will continue to evolve. For credit unions, success depends on how effectively they manage complexity while continuing to serve their members.
Reach out to NFP to learn how we can help credit unions with a personalized strategy.